Context & Current Net Worth
Before boring you with our entire life story, here’s a summary of me and my wife’s current situation. You can also learn more about us and the game of FI here.
In short, we’re a married couple in our mid-late twenties living in Sydney, Australia. We’ve been saving and investing for about 5 years, which coincides with when we both began our professional careers.
Below is a summary of our joint net worth and our investment history as of September 2026:
| Category | ($AUD) |
|---|---|
| Assets | $ 263,396 |
| Cash | $ 147,857 |
| Mutual Funds | $ 69,502 |
| Employer Shares | $ 39,980 |
| Kids Account | $ 3,850 |
| Commsec | $ 2,206 |
| Liabilities | $ 15,271 |
| HECS Debt | $ 15,271 |
| Net Worth | $ 248,124 |
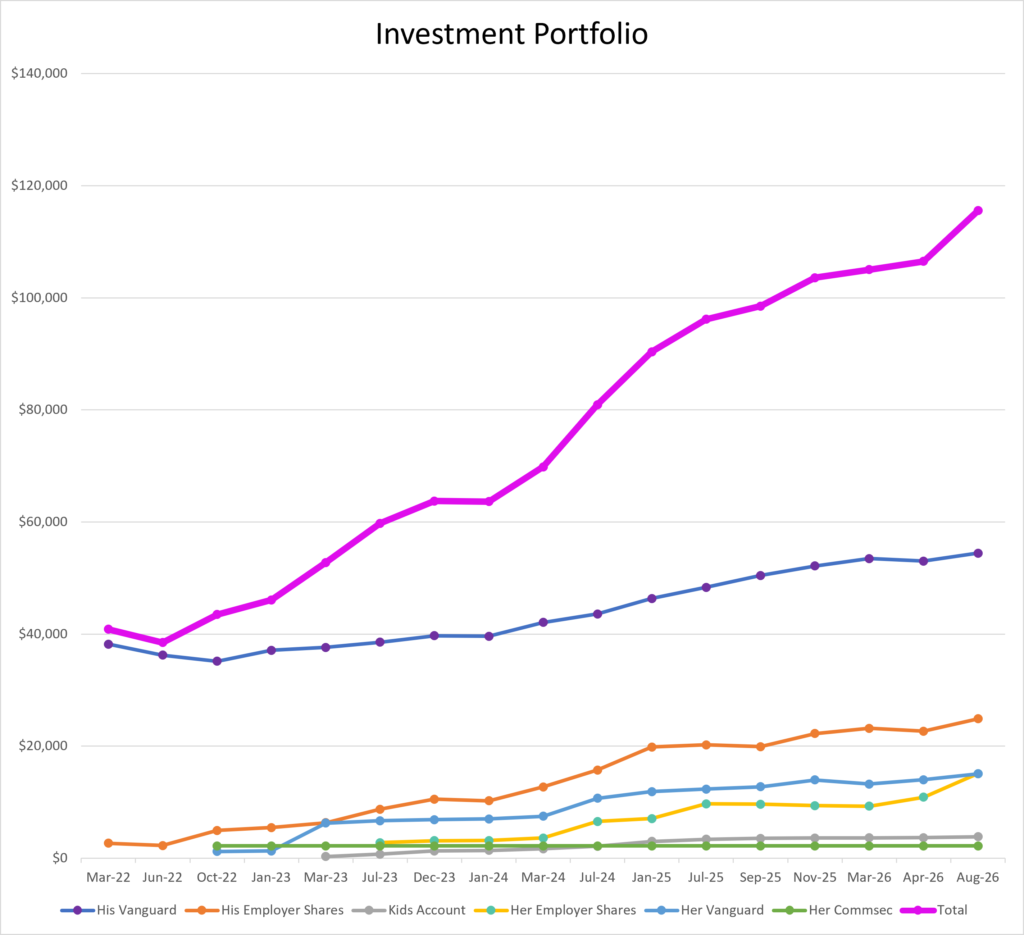
The majority of our net worth comes from cash savings, though we’ve also consistently invested and taken advantage of opportunities like our respective employee share plans.
We currently hold a large cash reserve (56% of total NW) with the intention to buy a home in the near future. I won’t go into further details about our investments here, as I’ll cover this later in a dedicated post.
Superannuation is excluded for simplicity, though I do believe you should include it in your own FIRE/retirement calculations if you intend to live past 60 years old.
Current Income & Expenses
| $AUD/month | |
|---|---|
| Post-Tax Income | $7,800 |
| Expenses | $6,500 |
We currently live on a single income since I’m pursuing a career change and recently started studying again. I expect to earn an entry level graduate salary shortly (~$70,000) once I begin work in my new field.
We live fairly modestly but do not budget hard. Our rent is relatively cheap for Sydney at $2,477/month, mostly because we rent a small 1-bedroom apartment (albeit in a nice suburb). We enjoy eating out on the weekends and trying new cafes, but otherwise we’re quite frugal.
Below is a more detailed account of our story and how we got to this point in time.
How we got here...
Stage 0 - Pre-FIRE
(Age 20; Jan 2019)
Individual Net Worth = $100
My individual journey began when I was 20 years old and single. At the time, I was appraoching my final year of university, and I’d just spent the first two years of my business degree coasting. I wasn’t a terrible student, but I certainly wasn’t living up to my potential.
Everything changed coming into my final year of university; possibly because I realised I’d have to find employment soon, or possibly due to something else entirely. Whatever changed, I took my study much more seriously and I couldn’t get my hands on enough finance, investing and business books. Something about financial markets, stocks, and investing was completely fascinating and drew me in.
It’s hard to pinpoint exactly when I learnt about FIRE, but I was gradually exposed to the concept through Australian finance creators like Aussie Firebug and RASK. Over time, it became second nature and occupied a lot of my thoughts.
Stage 1 - Learning, Earning & Building Momentum
(Age 21-23; Jan 2020-Mar 2022)
Individual Net Worth = -$5,498
| Category | $AUD/month | Comments |
|---|---|---|
| Post-Tax Income | $3,600-$3,800 | Full-time, single income |
| Expenses | $750 | LCOL city, living at home |
| Savings Rate | 77%-82%* | 82% includes 15% pre-tax SS to Super* |
| Amount Invested | $3,000 | Not including Super |
| Assets | $41,665 | Not including Super |
| Liabilities | $-47,163 | HECS Debt (gov subsidised loan for study) |
| Net Worth | $-5,498 |
This phase was pivotal in my FIRE journey as I built a strong financial base using my first full-time income.
In 2020, I worked part-time for over a year and used this money to build my emergency fund. From March 2021 onwards, I began working full-time and started to invest. I was able to squirrel away roughly $3,000 per month due to the immense privilege of living at home within a LCOL city.
I was also salary sacrificing 15% of my pre-tax income to Super (roughly $840/month which was 1.5x my compulsory employer contributions at the time).
While my net worth was technically negative, anyone in Australia will tell you this was a sound financial position due to the nature of our student loans.
At this time, my wife and I began dating, though we were still living apart with separate finances. I didn’t know it at the time, but my life and FIRE journey were going to take many unexpected twists and turns.
Stage 2 - Changing Life Circumstances and Priorities
(Age 21-23; Mar 2022-Aug 2026)
Combined Net Worth = $248,125
| Category | $AUD/month | Comments |
|---|---|---|
| Post-Tax Income | $8,100-$12,700 | Full-time, dual income, no kids. Growing incomes over time. |
| Expenses | $4,500-$6,100 | HCOL city, lifestyle inflation, actual inflation (e.g. +35% in rent) |
| Savings Rate | 50-55%* | Some fluctuation, 55% includes 10-15% SS on my income |
| Amount Invested | Minimal | ~$3,000 per year, not including monthly SS Super contributions |
| Wedding | $-50,000 | Traditional overseas wedding |
| Honeymoon | $-20,000 | Scandinavia, first time to Europe |
| Assets | $263,396 | Not including Super |
| Liabilities | $15,271 | HECS Debt (gov subsidised loan for study) |
| Net Worth | $248,125 |
Life changed more than I could ever imagine in this stage. My rigid FIRE ambitions were put to the side and deprioritised, probably for the best.
During this time, my wife and I moved to a HCOL city, travelled overseas multiple times, got married and have been planning our honeymoon. Up until this point, I had never travelled or lived away from home. It was a period filled with incredible life experiences which broadened my horizons. Despite slowing “my” FIRE progress, I’m extremely grateful for the choices I made.
Throughout this period, we loosely lived on 1 income (the lower of our 2 incomes) and saved the rest. This mostly funded our wedding, honeymoon and travelling, though we also saved a significant amount for our first home (currently $140,000+). Our house savings were significantly boosted by my FHSSS contributions ($47,000).
We took some important steps to ensure we were still progressing financially while living our best lives. First, we both contributed to our employer share schemes (employer matching). Second, I continued salary sacrificing while my income grew. Third, and most importantly, we left our investments to compound despite our temptation to sell (especially for a house deposit in Sydney!).
Our total wedding cost was $50,000, with a further $20,000 budgeted for our honeymoon. Others in the FIRE community will scoff, but for us, this was a valuable use of our money and we don’t regret this spend. Further to the above, we travelled overseas 5 times (including 3 trips to visit my wife’s family). We also hosted my in laws in Australia which was incredibly rewarding.
More than anything, I’m grateful that “my” journey has become our journey.
Stage 3 - Where to From Here?
Sep 2026-
In the short-term, we’re currently in a new and unexpected situation where we’re living off 1 income out of necessity rather than to save and/or invest. From here, I’d expect our savings rate to drop to as low as 10-15% in the coming months.
By the end of the year, I’m hoping we improve our savings rate back up to at least 30-40% when I begin a role in my new field.
Within 2 years, it’s very likely we’ll buy a home (PPOR) in Sydney since we’ve already accessed my FHSSS. The size of the mortgage and amount of cash tied up in our future home will heavily depend on how quickly we grow our household income (income will matter more than savings rate).
We’re both fairly frugal and committed to saving and investing. Despite the temporarily lower income, I’m quietly optimistic that we’ll progress even faster in the next 4 years than we have since moving to Sydney.
If you’d like to follow our FI journey, please subscribe to the mailing list and keep your eyes peeled for more content!